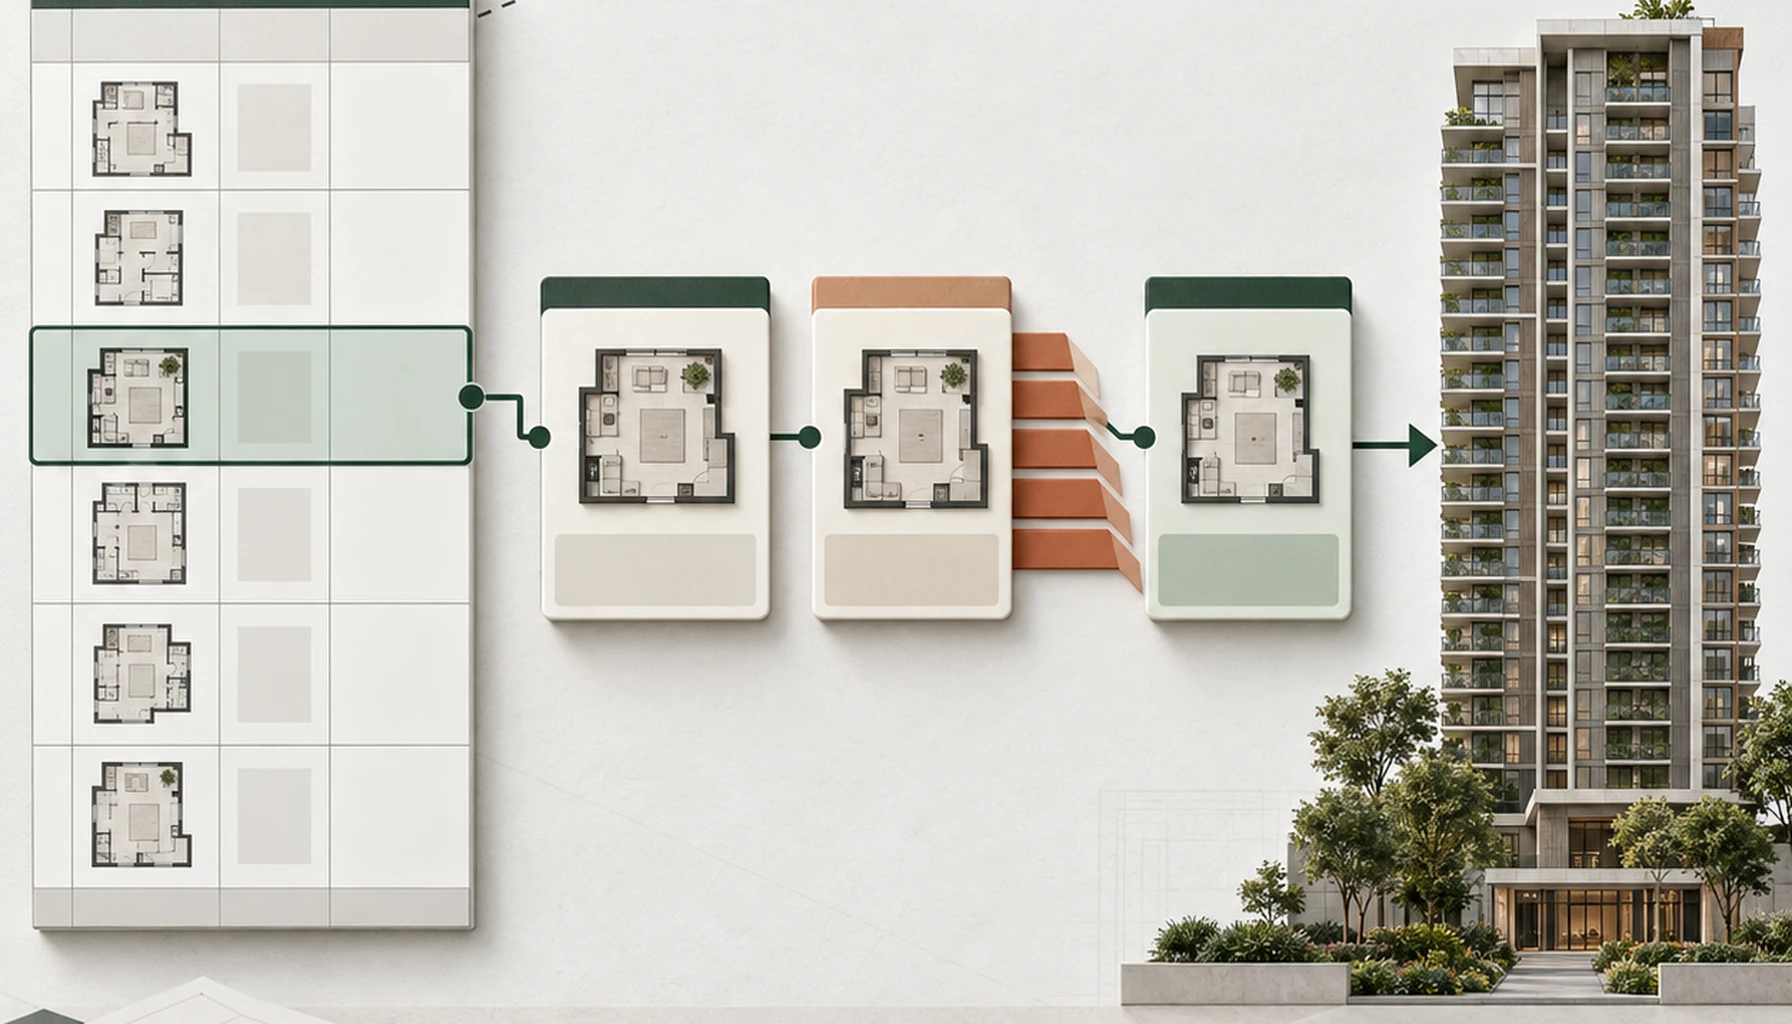
List Price Is Not Realized Price: How to Correct the Evidence Before Pricing
A development can display a strong price list while contracting units at different economic values. That does not prove the list is wrong. It shows that the…
Imovitec · September 26, 2026
A development can display a strong price list while contracting units at different economic values. That does not prove the list is wrong. It shows that the pricing team must reconcile distinct measures before deciding whether to maintain, raise or reduce prices.
The distinction becomes critical when external evidence comes from listings. Fundação Instituto de Pesquisas Econômicas, known as Fipe, states that the FipeZAP Index is calculated from property advertisements. Its movements therefore describe asking-price samples, not values confirmed in contracts, deeds or cash receipts.
Key takeaways
List price, contracted value, net management value and cash received answer different questions. FipeZAP supplies evidence about advertised prices, while internal contracts document accepted commercial terms. A defensible pricing review keeps those measures separate, applies consistent denominators and records every exclusion, deduction and unresolved field.
- Sourced fact: FipeZAP tracks advertised prices. It does not directly measure completed transaction prices.
- Analytical framework: List price, contracted value, net management value and cash received should remain separate.
- Inference: Asking prices alone may overstate realizable price, but neither the direction nor size of the difference can be assumed for a specific market.
- Evidence requirement: A pricing review needs historical lists, comparable contracts, consistent area definitions, documented incentives and explicit exclusion rules.
- Blocked assumption: No verified source in the approved evidence supports a universal average discount between list and closing price.
What is the difference between list price and realized price?
List price is the amount offered for a unit on a stated date. Realized price is an analytical term that must be defined before use, usually as the contracted value or a reconciled net value for the same unit. An external advertised price may never become a transaction.
| Measure | Definition | Main limitation |
|---|---|---|
| List price | Published unit price in a defined list version and date | Does not prove buyer acceptance |
| Contracted value | Amount stated in the comparable contract | May exclude monetized incentives and other deductions |
| Net management value | Contracted value less deductions defined by an approved management policy | Depends on complete data and accounting validation |
| Cash received | Receipts tied to contracts during a declared period | Is not contracted value or recognized revenue |
These four measures form an editorial framework for this article. The approved sources do not establish the complete taxonomy together. Its purpose is to stop unlike figures from entering the same comparison.
The same discipline applies to competitor data. A sales table indicates positioning, not closing. See how to read a competitor’s sales table without confusing list price with realized price.
Why can asking-price indicators not replace contract evidence?
An asking-price indicator observes offers within its documented sample. A contract records an accepted transaction under specific commercial conditions. The two sources answer related but different questions. Treating them as equivalent removes negotiation, incentives and contractual terms from the pricing analysis.
The Fipe institutional page says that the FipeZAP Index uses advertisement samples. Its 2019 methodology describes that source and calculation. Because the document is dated 2019, its coverage, filters and weighting should be checked against the current methodology before publication or reuse.
The November 2025 FipeZAP residential sales report published an average advertised price of R$9,585 per m² for ready apartments in its covered locations. That figure has a fixed period and scope. It is not a national contract, deed or cash-receipt price and cannot be transferred to another month or locality without new evidence.
As an analytical inference, asking-price data can help assess market positioning. Economic validation should give priority to comparable internal contracts and documented deductions. This does not mean that every property closes below its advertised price.
How should a pricing team reconcile list and contracted values?
Start with one unit and one historical list date, match that record to its contract and subtract only documented items under a consistent policy. Aggregate the records after completing the unit-level reconciliation. A missing value must remain unknown rather than silently becoming zero.
1. Lock the comparison basis
Record the development, phase, unit, unit type, relevant physical attribute, sales channel, contract date and historical list version. Select one area concept, such as private, usable or equivalent area, and apply it consistently.
Do not replace a missing historical list with today’s list. Block the price-per-square-metre calculation when a unit has no valid area. These controls prevent false differences caused by mismatched dates or denominators.
2. Calculate the nominal discount for the same unit
Nominal discount on list price equals list price minus contracted value, divided by that unit’s list price, then multiplied by 100.
Report the result as a percentage for the same contract and reference date. Two decimal places are suitable for presentation. Exclude records without a historical list or comparable contract and record the reason. The result describes a contractual difference, not the complete net economics.
3. Standardize contracted price per square metre
Contracted price per m² equals contracted value divided by the consistently selected area.
The result is expressed in R$/m² for the contract date. Use whole reais or two decimal places and round only the final result. Do not compare one unit measured by private area with another measured by usable or equivalent area.
4. Reconcile the net management value
Net management value equals contracted value minus additional discounts, monetized incentives, attributed commission and other defined deductions.
The result is stated in reais per unit. Divide it by the same area used for contracted price when reporting R$/m². Declare the contract period or cohort, retain unknown deductions as unknown and obtain accounting validation for the policy.
Upgrades, payment support and channel incentives should enter the bridge only when they have an authorized monetary value and explicit classification. Incentives, commissions, swaps, financial components and cancellations may require accounting and legal review.
The sources below establish what the cited indicators observe and define the scope of the November 2025 figure.
How can multiple contracts be compared without distorting the result?
Use a homogeneous cohort and calculate weighted price per square metre by dividing the sum of comparable values by the sum of their valid areas. This method gives each square metre equal weight. It is not interchangeable with a simple average of unit-level R$/m² figures.
Weighted average price per m² equals the sum of comparable values divided by the sum of comparable valid areas.
State whether the numerator contains contracted values or reconciled net values. Keep the segment and period consistent, round only the final result, and disclose the number of excluded records and their exclusion reasons.
Cuts by unit type, phase, sales channel or contract month can clarify differences. The approved sources provide no universal minimum sample size. Small samples should therefore be disclosed, not hidden behind an invented threshold.
A broader review should also connect pricing to the stock being sold. See how launch pricing can cross price per m², unit type, inventory and VSO.
Talk to a specialist
Want to see this applied to your case?
Instead of finishing the article and staying in theory, send us your situation on WhatsApp. We reply with the concrete next step.
How should the VGV bridge be reconciled?
The VGV bridge connects the list-price potential of one cohort to its reconciled net management value. It separates contractual discounts, monetized incentives, recognized cancellations and other defined deductions. When records are incomplete, the bridge should show the unknown items instead of being forced to close.
List VGV minus contractual discounts, monetized incentives, recognized cancellations or distratos, and other defined deductions equals reconciled net management value.
Present the bridge in reais and, when useful, as percentages of the list VGV for the same cohort. Use one time window and round only at the end. The percentage denominator must be the list VGV of that cohort.
Accounting treatment for cancellations, revenue and variable consideration requires professional review. A distrato must not be deducted automatically and in full from the original sales period. Readers establishing the starting measure can consult how to calculate a development’s VGV and document every assumption.
Do VSO or IVV reveal the realized price?
No. Sales-velocity indicators describe sales relative to a defined supply base. They do not reconcile list price, contracted value, net economics or cash received. Their period, denominator and treatment of cancellations must be stated before the result can support a pricing discussion.
For internal analysis, an editorial VSO can be stated as follows:
VSO equals sales during the declared period divided by initial supply plus launches during that period, multiplied by 100.
The denominator must consistently use either units or VGV. State the period, rounding rule and treatment of distratos, relaunches and incomplete inventory. Two decimal places are appropriate for presentation.
This formula has not been verified as the exact current ABRAINC/Fipe definition and must not be attributed to that institution without checking its methodology. ABRAINC/Fipe institutional material confirms monthly indicators for launches, sales, deliveries, final supply and distratos in the primary residential market reported by participating companies. It does not automatically represent the entire Brazilian market.
Before combining velocity and pricing conclusions, read VSO vs. IVV: which indicator to use, for what period, and what neither measures.
What should go into the next pricing meeting?
Bring a reconciled evidence table, an exclusion log and a VGV bridge. Separate supported conclusions from hypotheses. The decision is whether comparable evidence supports maintaining or correcting the list, not whether one advertised-price or sales-velocity indicator moved during the period.
The meeting pack should contain:
- Historical list version and reference date for every included unit.
- Comparable contract, area concept, unit type, phase and sales channel.
- Contracted and net values, with every deduction documented.
- Weighted R$/m² for a declared homogeneous cohort.
- Missing fields, exclusions and unresolved reconciliation differences.
- Separate views of advertised evidence, contracted sales, net economics and cash receipts.
Avoid universal discount assumptions, unsupported claims about interest rates and automatic accounting rules for distratos. The approved evidence does not support them.
The soundest pricing decision is not the one with the most precise-looking number. It is the one in which every figure retains its source, denominator, period, scope and limitation.
Sources and limitations
The sources below establish what the cited indicators observe and define the scope of the November 2025 figure. They do not supply internal contract economics, a universal closing discount or automatic accounting rules. Current methodology and project-level records must be checked before a pricing decision.
- Fipe, “Índice FipeZAP”. Publication date not stated; accessed September 26, 2026. Scope: advertised residential and commercial properties for sale and rent in Brazil.
- Fipe, “Índice FipeZAP Methodology”. Version identified as 2019; accessed September 26, 2026. Confirm the current methodology and coverage before reuse.
- Fipe/FipeZAP, Residential Sales Report, November 2025. Scope: advertised ready apartments in covered locations. The R$9,585/m² figure is an asking-price average.
- ABRAINC/Fipe, “Indicador Mensal”. Updated monthly; specific reference period not captured; accessed September 26, 2026. Scope: primary residential market reported by participating companies.
FAQ
How do I price a real-est estate development correctly when list and contracted prices differ?
Correct pricing starts by comparing like-for-like evidence. Reconcile the historical list price with the contracted value for the same unit and date, then account for documented incentives and deductions. Segment contracts by development phase, typology, area, channel and cohort before deciding whether to maintain or revise the price list.
What formula calculates the actual selling price of a property?
No single formula represents every meaning of actual selling price. Contracted price per square meter equals contracted value divided by a consistently defined area. Nominal discount equals the list price minus contracted value, divided by list price. A net management price may require additional documented deductions and accounting validation.
What's the best way to compare asking prices with actual property sales?
The best comparison keeps asking-price and transaction evidence separate. Fipe states that FipeZAP uses property advertisements, so its figures represent asking-price samples rather than confirmed transactions. Compare that external benchmark with homogeneous internal contracts, using aligned dates, locations, property types and area definitions, while reporting gaps and exclusions explicitly.
Is the FipeZAP price the amount buyers actually pay for a property?
FipeZAP does not directly measure the amount confirmed in contracts, deeds or cash receipts. Fipe describes the index as being calculated from property advertisements. It can indicate asking-price movements within its sample and coverage, but it should not be presented as evidence of realized prices or universal negotiation discounts.
How should a developer reconcile list-price VGV with realized commercial value?
Reconciliation should build a documented bridge from list-price VGV to the chosen net management measure. Show contractual discounts, monetized incentives, recognized cancellations and other defined deductions separately for the same cohort and period. Unknown items must remain visible rather than being treated as zero, and accounting classifications require appropriate review.
Is reconciling contracted and net prices worth the time and cost?
Reconciliation is valuable when a pricing decision could overstate realizable value or trigger an unsupported price reduction. A focused review can prioritize the current cohort, material deductions and comparable units. Its return should be assessed through decision quality and avoided exposure, since no universal savings or ROI percentage is supported by the supplied evidence.
Can market asking-price data replace internal contracts when revising a development's price list?
Asking-price data cannot replace internal contracts for measuring accepted commercial terms. External indicators provide market context, while contracts, historical price lists and documented deductions support project-level economic validation. If coverage, dates, areas or cohorts are incompatible, the conclusion should be qualified or postponed rather than forced from incomplete evidence.
Talk to a specialist
Have a real case to solve?
Message Imovitec on WhatsApp. We reply fast and already speak your context — no forms, no waiting.
Frequently asked questions
How do I price a real-est estate development correctly when list and contracted prices differ?
Correct pricing starts by comparing like-for-like evidence. Reconcile the historical list price with the contracted value for the same unit and date, then account for documented incentives and deductions. Segment contracts by development phase, typology, area, channel and cohort before deciding whether to maintain or revise the price list.
What formula calculates the actual selling price of a property?
No single formula represents every meaning of actual selling price. Contracted price per square meter equals contracted value divided by a consistently defined area. Nominal discount equals the list price minus contracted value, divided by list price. A net management price may require additional documented deductions and accounting validation.
What's the best way to compare asking prices with actual property sales?
The best comparison keeps asking-price and transaction evidence separate. Fipe states that FipeZAP uses property advertisements, so its figures represent asking-price samples rather than confirmed transactions. Compare that external benchmark with homogeneous internal contracts, using aligned dates, locations, property types and area definitions, while reporting gaps and exclusions explicitly.
Is the FipeZAP price the amount buyers actually pay for a property?
FipeZAP does not directly measure the amount confirmed in contracts, deeds or cash receipts. Fipe describes the index as being calculated from property advertisements. It can indicate asking-price movements within its sample and coverage, but it should not be presented as evidence of realized prices or universal negotiation discounts.
How should a developer reconcile list-price VGV with realized commercial value?
Reconciliation should build a documented bridge from list-price VGV to the chosen net management measure. Show contractual discounts, monetized incentives, recognized cancellations and other defined deductions separately for the same cohort and period. Unknown items must remain visible rather than being treated as zero, and accounting classifications require appropriate review.
Is reconciling contracted and net prices worth the time and cost?
Reconciliation is valuable when a pricing decision could overstate realizable value or trigger an unsupported price reduction. A focused review can prioritize the current cohort, material deductions and comparable units. Its return should be assessed through decision quality and avoided exposure, since no universal savings or ROI percentage is supported by the supplied evidence.
Can market asking-price data replace internal contracts when revising a development's price list?
Asking-price data cannot replace internal contracts for measuring accepted commercial terms. External indicators provide market context, while contracts, historical price lists and documented deductions support project-level economic validation. If coverage, dates, areas or cohorts are incompatible, the conclusion should be qualified or postponed rather than forced from incomplete evidence.
Imovitec
Turn data into next steps.
Take the Imovitec diagnostic and see where your best opportunities are.