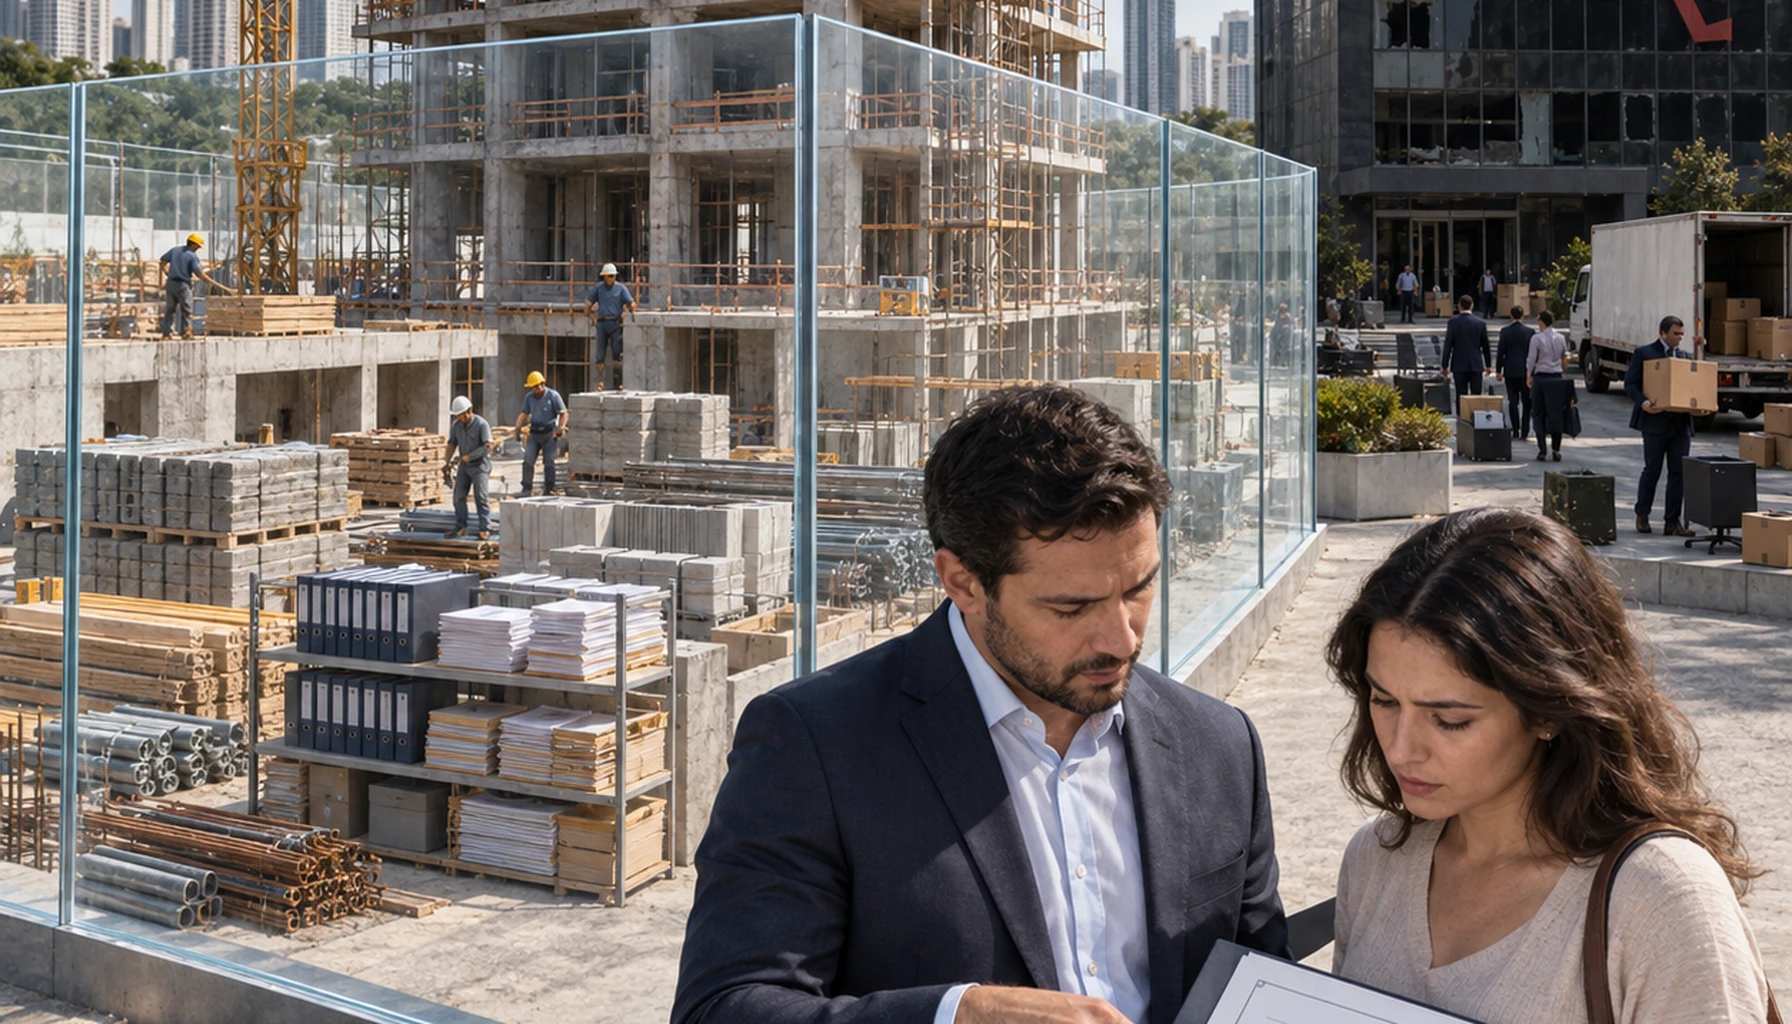
Patrimônio de Afetação: What Changes for Off-Plan Buyers if the Developer Fails?
An off-plan buyer is not automatically guaranteed a finished unit or full repayment if a Brazilian developer fails. The outcome depends partly on whether the…
Imovitec · September 17, 2026
An off-plan buyer is not automatically guaranteed a finished unit or full repayment if a Brazilian developer fails. The outcome depends partly on whether the development formally entered the patrimônio de afetação regime and whether the segregated estate can meet the project’s obligations.
Concise definition: Patrimônio de afetação is the legal separation of a development’s assets and rights from the developer’s general estate.
Articles 31-A to 31-F of Federal Law 4,591/1964 govern the regime. Federal Law 10,931/2004 introduced the corresponding chapter. Within the limits of the statute and the case, this separation can shield construction assets from liabilities unrelated to that development. It is not insurance.
Key takeaways
For a broker comparing launches, the distinction matters: patrimônio de afetação changes the legal treatment of project assets, yet construction, funding and delivery risks remain. Current registry and development records should establish whether the regime exists. Its limits should be stated just as clearly.
- The regime does not arise automatically in every off-plan development. Article 31-A says an incorporation may enter it at the developer’s discretion.
- Its core function is to separate affected project assets and rights from the developer’s general estate, subject to the applicable legal framework.
- Developer failure may lead to a collective process involving the construction project, the segregated estate and purchasers. It does not produce an automatic individual refund.
- The available evidence establishes no unconditional assurance of completion, on-time delivery or full repayment.
- A special purpose entity, or SPE, is distinct from patrimônio de afetação. The Special Tax Regime, or RET, is another separate arrangement.
- Precise insolvency, registry and financing consequences require analysis of current law and the documents for the particular development.
These conclusions draw on the consolidated legislation published by Brazil’s Chamber of Deputies and institutional reports from the Superior Court of Justice. Important procedural and registry questions still require legal confirmation. Those limits are identified below.
What is patrimônio de afetação?
Patrimônio de afetação is a statutory arrangement under which the assets and rights of one incorporation occupy a separate project estate. Articles 31-A to 31-F of Federal Law 4,591/1964 define its legal boundaries and distinguish that economic sphere from the developer’s general holdings.
What cannot be inferred from an off-plan sale alone? The existence of the regime. Article 31-A makes submission discretionary for the developer, so neither an SPE nor references to structured governance in sales material prove that the project has an affected estate.
The Chamber of Deputies’ consolidated version of Federal Law 4,591/1964 identifies Federal Law 10,931/2004 as the legislation that introduced the chapter. Because a consolidated text may incorporate later amendments, its wording in force should be confirmed before publication, professional guidance or a transaction.
What changes if the developer fails?
Where the regime was validly constituted, affected project assets are treated separately from the developer’s general estate under the statutory framework. That shifts the legal starting point. It does not show that the estate contains enough money to finish construction or repay every purchaser.
Articles 31-A to 31-F, read as a structure, support the conclusion that the response entails a collective process connected with the development, its segregated assets and its purchasers. This remains a legal inference, not a forecast for any particular insolvency.
Specific procedure is where caution becomes decisive. Before stating deadlines, voting thresholds, payment priority, representatives’ authority, auction rules or further purchaser obligations, the current text of Article 31-F must be reviewed. The approved source package does not establish those details.
A broker should avoid two categorical claims:
- “The building will definitely be completed.”
- “Every buyer will automatically receive all money back.”
The eventual position may turn on the estate’s sufficiency, unfinished construction costs, development finance, collective decisions and implementation of the governing process. Any one of those factors could materially alter the buyer’s outcome.
Does patrimônio de afetação guarantee completion or a full refund?
The reviewed sources establish no absolute guarantee. Asset segregation and a statutory process may change how a failure is handled, but they do not justify a promise of completion, punctual delivery or full reimbursement in every case. Even a segregated development may encounter a funding gap, operational interruption, litigation or project-specific liabilities.
Useful distinction, yes. Insurance, no.
A Superior Court of Justice report dated October 18, 2024, says that ending the affected estate requires satisfaction of obligations owed to the development’s financing agent. The practical consequence is significant: an assessment cannot consider purchasers’ payments in isolation.
Still, the source is an institutional account of a Fourth Panel judgment rather than the full ruling. Its reasoning should not be applied to a transaction until the judgment, procedural posture and later developments have been checked.
How can a buyer verify whether the regime exists?
Verification should come from current records for the specific development, not from a brochure or verbal assurance. Since the arrangement is optional and requires formal constitution, the buyer and broker should obtain the incorporation and registry material, then seek professional confirmation of the entry that proves constitution in that particular case.
A practical document review can cover:
- a current certificate for the property’s registration record;
- the registered incorporation documents and amendments;
- identification of the developer and any SPE;
- available agreements and information concerning construction finance;
- the record presented as evidence that the affected estate was constituted;
- registered liens, encumbrances and material annotations;
- consistency among the registry, contract, summary box and sales material.
Reviewing the registration record is a practical inference from the regime’s formal character. The approved research did not recover the precise current wording for the relevant registry act. A Brazilian real estate registry specialist should therefore confirm which certificate and annotation serve as proof.
The inquiry should also reach risks beyond insolvency. See How to Read a Brazilian Developer Sales Table Before Buying Off-Plan and Total Cost of an Off-Plan Property in Brazil for two related checks.
Talk to a specialist
Want to see this applied to your case?
Instead of finishing the article and staying in theory, send us your situation on WhatsApp. We reply with the concrete next step.
Is an SPE the same as patrimônio de afetação?
No. An SPE is a legal entity created for a defined project. Patrimônio de afetação, by contrast, is a statutory regime that segregates the assets and rights of an incorporation. An SPE’s presence alone does not demonstrate that an affected estate exists.
A Superior Court of Justice report from May 24, 2022, addresses circumstances in which real estate SPEs may enter judicial reorganization. The reported treatment varies according to the existence of patrimônio de afetação, which supports treating the two structures separately. Application beyond the adjudicated facts requires examination of the full judgment.
RET is different as well. It concerns tax treatment. No current rate, option or eligibility requirement should be stated without consulting the tax legislation and Brazilian Federal Revenue rules applicable at the relevant date.
For commercial purposes, the accurate explanation is concise: an SPE identifies a project-specific company, patrimônio de afetação concerns legal segregation of assets, and RET concerns taxation. Each calls for its own evidence.
Is developer insolvency the same as a distrato?
Developer insolvency and purchaser cancellation are separate legal events. Retention rules associated with a distrato cannot simply be imported into an insolvency assessment. Nor do the reviewed sources support a fixed repayment percentage after a developer’s failure.
Why does that distinction matter? Borrowing a percentage from cancellation law could distort the buyer’s understanding of both the segregated estate and the relevant collective procedure. For the separate cancellation question, read Brazil’s Distrato Law: What Can Be Retained After a Property Cancellation?.
Before signature, consider the current Articles 31-A to 31-F, registry evidence and project documentation together.
What should a broker explain before signature?
A broker should distinguish what the records establish from what remains unresolved. This means explaining asset segregation, identifying uncertainty and saying plainly that the regime creates no automatic assurance of completion or full repayment. Qualified Brazilian professionals should assess transaction-specific legal consequences.
A defensible conversation covers four points:
- Confirm whether the particular development formally constituted patrimônio de afetação.
- Explain the separation of project assets from the developer’s general estate under Federal Law 4,591/1964.
- State that segregation does not ensure automatic completion or full repayment.
- Refer insolvency, financing and registry consequences to the appropriate legal and registry specialists.
Keep the supporting records and note when each was issued. A stale certificate should never be described as current. Where the regime cannot be proved, the precise description is “not verified,” not “probably protected.”
What is the decision rule when comparing launches?
Treat verified patrimônio de afetação as a meaningful legal distinction, not as a complete risk score. The comparison should examine whether the regime exists, what proves it, which financing arrangements and encumbrances appear in current records, and whether the contract accurately reflects the development structure.
The evidence permits a qualified conclusion: patrimônio de afetação can separate project assets from the developer’s general estate and shape the response to failure. In the middle of that protection lies its limit. Construction, financing and execution risks do not disappear.
Before signature, consider the current Articles 31-A to 31-F, registry evidence and project documentation together. If bankruptcy or judicial reorganization could change the purchasing decision, advice from qualified Brazilian counsel is essential.
Sources and limitations
- Brazilian Chamber of Deputies, Federal Law 4,591 of December 16, 1964, consolidated text, accessed September 17, 2026. Scope: Brazilian condominiums and real estate developments. Limitation: confirm the current wording of Articles 31-A to 31-F directly.
- Brazilian Chamber of Deputies, Federal Law 10,931 of August 2, 2004, original publication, accessed September 17, 2026. Limitation: the original publication alone does not establish the current consolidated wording.
- Superior Court of Justice, Termination of the affected estate requires payment of financing obligations, October 18, 2024. Limitation: institutional news summary; check the full judgment and subsequent procedural developments.
- Superior Court of Justice, Submission of a real estate SPE to judicial reorganization, May 24, 2022. Limitation: do not generalize beyond the judgment’s facts and legal grounds.
FAQ
How does patrimônio de afetação work when buying an off-plan property in Brazil?
Patrimônio de afetação legally separates a development’s assets and rights from the developer’s general estate. Under Articles 31-A to 31-F of Federal Law 4,591/1964, this separation can shield project assets from unrelated obligations. It does not insure completion, timely delivery, or a full refund.
What is the difference between an SPE and patrimônio de afetação?
An SPE is a legal entity created for a specific project, while patrimônio de afetação is a statutory segregation of a development’s assets and rights. The structures are not interchangeable, and neither should be confused with Brazil’s special tax regime. Brokers should verify each arrangement separately before explaining project risk.
What’s the best way to check whether a development has patrimônio de afetação?
The safest approach is to request current registry evidence and the development’s incorporation documents, then obtain legal review when wording or encumbrances are unclear. The regime is optional and must not be presumed from advertising, an SPE, or a tax arrangement. Verification should concern the specific development being offered.
What happens to off-plan buyers if the developer goes bankrupt?
Buyers do not automatically receive a completed unit or a full refund when a developer fails. If the development has patrimônio de afetação, its segregated estate follows a collective statutory procedure connected to the project. The practical outcome depends on available assets, obligations, buyer decisions, and the current legal framework.
When does patrimônio de afetação end?
Patrimônio de afetação does not necessarily end when construction finishes or units are delivered. Brazil’s Superior Court of Justice reported in 2024 that obligations to the project’s financing agent must be discharged before termination. Other statutory conditions should be confirmed against the current legislation and reviewed for the specific development.
Is checking patrimônio de afetação worth the cost before recommending a launch?
Verification is a risk-control step, not a guarantee of investment return. For brokers, reviewing current registry evidence, incorporation documents, and legal uncertainties helps prevent unsupported promises about completion or reimbursement. The appropriate diligence cost depends on the transaction, while the commercial and legal consequences of misleading a buyer may be substantial.
Can a broker use the same patrimônio de afetação explanation for every development?
A generic explanation is insufficient because the regime is optional and project-specific. Brokers should confirm the applicable registry evidence, incorporation documents, financing obligations, and current legal text for each launch. Questions involving bankruptcy procedures, voting rules, payment priorities, or additional buyer liability require qualified legal review rather than standardized sales claims.
Talk to a specialist
Have a real case to solve?
Message Imovitec on WhatsApp. We reply fast and already speak your context — no forms, no waiting.
Frequently asked questions
How does patrimônio de afetação work when buying an off-plan property in Brazil?
Patrimônio de afetação legally separates a development’s assets and rights from the developer’s general estate. Under Articles 31-A to 31-F of Federal Law 4,591/1964, this separation can shield project assets from unrelated obligations. It does not insure completion, timely delivery, or a full refund.
What is the difference between an SPE and patrimônio de afetação?
An SPE is a legal entity created for a specific project, while patrimônio de afetação is a statutory segregation of a development’s assets and rights. The structures are not interchangeable, and neither should be confused with Brazil’s special tax regime. Brokers should verify each arrangement separately before explaining project risk.
What’s the best way to check whether a development has patrimônio de afetação?
The safest approach is to request current registry evidence and the development’s incorporation documents, then obtain legal review when wording or encumbrances are unclear. The regime is optional and must not be presumed from advertising, an SPE, or a tax arrangement. Verification should concern the specific development being offered.
What happens to off-plan buyers if the developer goes bankrupt?
Buyers do not automatically receive a completed unit or a full refund when a developer fails. If the development has patrimônio de afetação, its segregated estate follows a collective statutory procedure connected to the project. The practical outcome depends on available assets, obligations, buyer decisions, and the current legal framework.
When does patrimônio de afetação end?
Patrimônio de afetação does not necessarily end when construction finishes or units are delivered. Brazil’s Superior Court of Justice reported in 2024 that obligations to the project’s financing agent must be discharged before termination. Other statutory conditions should be confirmed against the current legislation and reviewed for the specific development.
Is checking patrimônio de afetação worth the cost before recommending a launch?
Verification is a risk-control step, not a guarantee of investment return. For brokers, reviewing current registry evidence, incorporation documents, and legal uncertainties helps prevent unsupported promises about completion or reimbursement. The appropriate diligence cost depends on the transaction, while the commercial and legal consequences of misleading a buyer may be substantial.
Can a broker use the same patrimônio de afetação explanation for every development?
A generic explanation is insufficient because the regime is optional and project-specific. Brokers should confirm the applicable registry evidence, incorporation documents, financing obligations, and current legal text for each launch. Questions involving bankruptcy procedures, voting rules, payment priorities, or additional buyer liability require qualified legal review rather than standardized sales claims.
Imovitec
Turn data into next steps.
Take the Imovitec diagnostic and see where your best opportunities are.