Real Estate Consortium Contemplation by Draw or Bid: What Changes in Practice?
A buyer tells the broker that their Brazilian real estate consortium quota has been contemplated. That matters, but it does not mean the seller will receive…
Imovitec · September 08, 2026
A buyer tells the broker that their Brazilian real estate consortium quota has been contemplated. That matters, but it does not mean the seller will receive payment immediately. Nor does it establish that every property is eligible for the transaction.
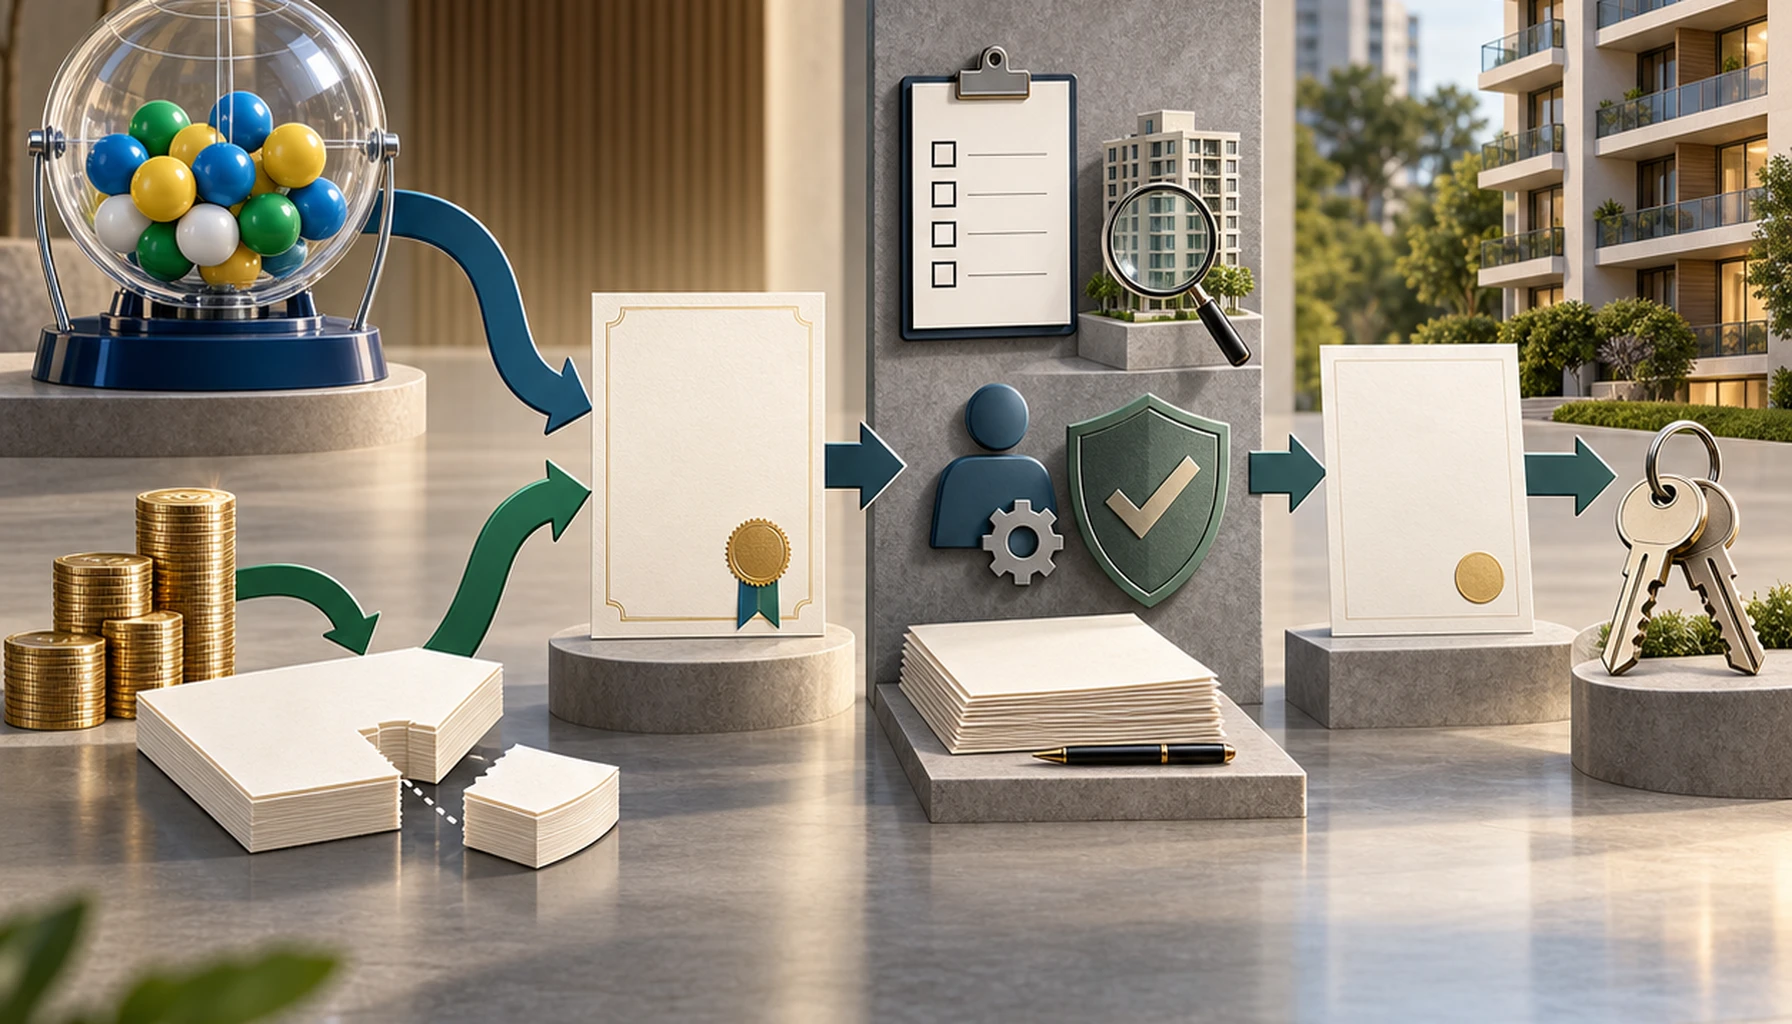
Under Brazil’s Consortium Law, contemplation attributes credit to the consortium member for acquiring a good or service. It can occur by draw or bid, depending on the group’s resources and contractual rules. The route changes the buyer’s financial position, especially with an embedded bid, but both routes lead to the administrator’s verification process before payment.
Key takeaways
Contemplation starts the purchasing stage, but the quota, buyer, guarantees and property may still require approval. Brokers should base negotiations on the administrator’s current documents, not merely on a contemplation notice. The source package establishes no universal release period, winning-bid percentage or guaranteed contemplation date.
- A draw does not, by itself, consume part of the contracted credit.
- An own-funds bid requires separate liquidity and any expressly applicable contractual charges.
- An embedded bid reduces the net credit available for the property.
- Credit values and installments may change under the adjustment criterion specified in the contract.
- The buyer may need to cover a gap between released net credit and the total documented acquisition cost.
- A purchase proposal should reflect the administrator’s actual approval and payment conditions.
What does contemplation mean in a Brazilian real estate consortium?
Contemplation is the attribution of consortium credit to a member for acquiring a good or service. It is not unrestricted cash or an automatic payment to the seller. The credit remains subject to the applicable law, current regulation, quota contract and administrator procedure.
This definition comes from Brazil’s Law No. 11,795 of October 8, 2008, published on October 9, 2008. The law governs the Consortium System nationally. It does not replace a review of the specific contract or current consolidated regulation.
A consortium is group-based self-financing administered by a company authorized and supervised by the Central Bank of Brazil. The Central Bank’s consumer guidance, What is a consortium administrator?, explains that contemplation occurs by draw or bid. Its update date was not confirmed in the supplied research, so the law, current regulation and contract remain decisive.
The contemplated member may select a supplier and a good within the contracted category, subject to legal and contractual conditions. A broker should therefore confirm that the proposed property meets the administrator’s requirements before presenting the credit as confirmed purchasing capacity.
What changes when contemplation occurs by draw?
In a draw, the member is selected without making a winning bid. The selection therefore does not itself consume part of the credit. This is a comparative inference from the draw and bid rules, not proof that the full nominal credit is immediately available for a property purchase.
The draw comes first in the assembly’s contemplation sequence. Under Central Bank of Brazil Resolution No. 285 of January 19, 2023, whose effective date was reported as January 1, 2024, bid contemplation follows draw contemplation or occurs when insufficient group resources prevent a draw.
That statement should be checked against the resolution’s current consolidated text before publication or use in a transaction. Contractual rules also matter.
A draw preserves the credit from bid-related deductions. Even so, the figure printed on an older proposal may no longer be current. Credit and installments can be adjusted by the index or criterion specified in the contract, so the operative amount must come from a dated administrator statement.
Future installments, contractual guarantees and property analysis do not disappear after a draw. Describing a drawn member as having “cash in hand” would misstate the restricted purpose of consortium credit.
For planning before contemplation, read Consortium Contemplation Is Not Guaranteed: How to Plan for Draws, Bids, and Delays.
What changes when contemplation occurs through a bid?
A winning bid can bring the member to contemplation under the group’s rules, but its financial effect depends on the source of the funds and the contract’s allocation method. The supplied official sources support no universal ideal percentage, fixed chance of winning or guaranteed contemplation date.
Bid paid with the member’s own funds
An own-funds bid requires a separate payment from the contemplated member. The required cash consists of the accepted bid plus only the charges expressly stated in the applicable documents. When the contract or statement is unavailable, charges must remain an unresolved item rather than being treated as zero.
Own cash outlay equals the bid paid with the member’s funds plus expressly applicable contractual charges.
Use the winning proposal, assembly rules and contract as inputs. The unit is Brazilian reais, and the reference date is the contractual payment deadline following the relevant assembly. Round the result to cents only after adding every verified component.
The effect on the outstanding balance, installment or remaining term is contract-specific. Statements from before and after the assembly are needed. A broker should not promise that the nominal bid will reduce any one variable by the same amount.
For related housing-finance context, see Brazilian Mortgage Financing in 2026: SBPE, FGTS and How Selic Affects a Purchase.
Embedded bid
An embedded bid uses part of the quota’s current credit as the bid. Under the applicable consortium rules, that amount is allocated to future installments. The resulting reduction in property purchasing power is an arithmetic inference from the regulatory treatment of the embedded bid.
Net credit equals the credit current on the assembly date minus the embedded-bid amount.
Both figures must concern the same quota and assembly date and must come from the administrator’s statement and contract. Use Brazilian reais and round to cents only after subtraction. If either figure is missing, do not calculate the result.
An embedded bid is not free. It may reduce the buyer’s immediate need for outside cash, but it leaves less consortium credit for the property. Other effects depend on the contract’s allocation rules.
Is contemplated credit released immediately?
No universal rule in the supplied sources establishes immediate release or a fixed number of days. Contemplation gives the member the right to use credit within the consortium system, while acquisition documents, guarantees, property review and payment to the seller follow the administrator’s documented procedure.
Law No. 11,795/2008 and Resolution No. 285/2023 support the administrator’s ability to require guarantees under the applicable legal, regulatory and contractual rules. The type, sufficiency and review period are not universal.
The administrator may also need to examine the member, seller, title documents, transaction structure and property valuation. These operational requirements can affect the closing schedule.
A purchase proposal should state that consortium payment is subject to the administrator’s procedure when that is the real condition. The contemplation notice alone is not a sound basis for promising a closing date.
How should a broker verify purchasing power after contemplation?
Purchasing power is the net credit that can actually be released compared with the property price and documented expenses the credit will not cover. Before recommending a property or negotiating a closing date, the broker should reconcile current quota, buyer, guarantee and property documents.
Request:
- The current contract and group or assembly rules.
- The updated quota statement and contemplation record.
- The administrator’s current credit statement.
- The bid proposal and proof of payment, when applicable.
- Current buyer, guarantee and property requirements.
- The agreed property price, title documents and expected valuation.
- A separate list of transfer tax, registry, valuation, insurance and other expenses, stating which items the credit may cover.
The buyer’s supplement is the greater of zero and the total acquisition price plus documented uncovered expenses minus the net credit effectively released.
This calculation applies to one acquisition at the expected closing date. Use Brazilian reais and round to cents at the end. Keep transfer tax, registration, valuation, insurance and other costs separate. If released net credit or any expense is unknown, mark it as pending instead of inserting an estimate.
Updating the credit requires the index named in the contract, its official series and the contractual adjustment dates. Do not substitute a generic inflation measure for a missing contractual index.
For a broader cash-flow review, read Real Estate Consortium in Brazil: How to Connect the Credit Letter, Construction and Cash Flow.
Talk to a specialist
Want to see this applied to your case?
Instead of finishing the article and staying in theory, send us your situation on WhatsApp. We reply with the concrete next step.
Can consortium credit repay a mortgage or be combined with FGTS?
A contemplated member may use consortium credit to repay financing in that member’s own name, subject to administrator consent and current regulatory conditions. FGTS use is a separate issue governed by the fund’s rules, transaction purpose and current eligibility requirements, not by contemplation alone.
The financing repayment possibility is supported by Law No. 11,795/2008 and the Central Bank’s historical note, BC regulates the new consortium law. Because the note concerns the 2009 regulatory setting, the transaction must be checked against current regulation, the contract and the administrator’s procedure.
Caixa Econômica Federal’s page, Use of FGTS for home ownership, presents general conditions. Its version date was not confirmed in the source package. Worker and property eligibility, permitted purpose, limits, intervals and documents must be checked under the operational manual in force on the transaction date.
For related housing-finance context, see Brazilian Mortgage Financing in 2026: SBPE, FGTS and How Selic Affects a Purchase.
Draw or bid: which option is better?
Neither route is universally better. A draw avoids a bid-related payment or deduction, but its timing cannot be promised. An own-funds bid consumes liquidity. An embedded bid can preserve immediate cash while reducing the net credit available for the property.
A responsible comparison considers liquidity, opportunity cost, contractual credit adjustments, remaining installments, property price, uncovered expenses and the buyer’s time horizon. The supplied evidence does not establish that bidding always pays off or that a draw is always financially superior.
The broker should move to property selection and negotiation only when current documents show sufficient net credit, an affordable supplement, an eligible property, acceptable guarantees and a workable administrator process. Contemplation opens the purchasing stage. Verification determines whether that quota can close that transaction.
Sources and limitations
This article is based on Law No. 11,795/2008, Central Bank of Brazil Resolution No. 285/2023, Central Bank consumer guidance and historical regulatory context, plus Caixa Econômica Federal’s general FGTS guidance. The supplied source record states that all were accessed on September 8, 2026.
These national legal and institutional sources do not replace the current quota contract, consolidated regulation, administrator instructions, financial review or legal advice for a particular transaction. No universal release period, winning-bid percentage or fixed contemplation probability was established. Current legal, financial, operational and FGTS reviews remain necessary before reliance in an actual purchase.
FAQ
How do I know whether a draw or a bid is better for my property consortium?
Neither method is universally better. A draw preserves the contracted credit but offers no predictable contemplation date. A successful own-funds bid requires additional cash, while an embedded bid reduces the credit available for the property. Compare liquidity, opportunity cost, contract rules, updated credit and the buyer’s intended purchase price.
What is the difference between contemplation by draw and by bid?
A draw selects eligible consortium members according to the group’s rules, while a bid involves competing through an offered amount. Both routes attribute the right to use the consortium credit, subject to contractual procedures. Neither automatically guarantees immediate payment because the administrator may still review the buyer, guarantees, documents and property.
I was selected in a property consortium. What do I do next?
Contact the administrator and obtain the updated quota statement, credit statement and current purchasing requirements. Then verify the available credit, required guarantees, eligible property category, documentation, appraisal and seller-payment procedure. The broker should confirm these conditions before promising a closing date or treating contemplation as immediately available cash.
How does an embedded bid affect the property credit?
An embedded bid uses part of the consortium credit to secure contemplation, so the net amount available for purchasing the property becomes smaller. Calculate it using the credit valid at the meeting minus the embedded-bid amount, both documented by the administrator. Any remaining purchase price and uncovered expenses require separate funding.
How long does it take to receive the credit after contemplation?
There is no verified universal deadline for releasing consortium credit after contemplation. Timing depends on the contract, administrator procedures, guarantees, property appraisal, documents and payment process. Brokers should request the current operational schedule directly from the administrator and align the offer and closing terms with documented milestones rather than an estimated date.
Is making a bid worthwhile if the client wants to buy a property soon?
A bid is worthwhile only when the client’s liquidity, opportunity cost and resulting purchasing capacity support it. Review the contractual bid base, payment deadline, updated credit and any embedded portion. Do not rely on a universal winning percentage or promised date; compare the net credit with the property price and uncovered transaction expenses.
What’s the best way to confirm that a contemplated consortium can be used for a specific property?
Confirm applicability with the administrator before the buyer commits to the property. Review the current contract and regulations, quota statement, credit statement, guarantees, property eligibility, required documents, appraisal and seller-payment process. Also calculate any funding gap using the total acquisition price, documented uncovered expenses and net credit effectively available for release.
Related reading
Talk to a specialist
Have a real case to solve?
Message Imovitec on WhatsApp. We reply fast and already speak your context — no forms, no waiting.
Frequently asked questions
How do I know whether a draw or a bid is better for my property consortium?
Neither method is universally better. A draw preserves the contracted credit but offers no predictable contemplation date. A successful own-funds bid requires additional cash, while an embedded bid reduces the credit available for the property. Compare liquidity, opportunity cost, contract rules, updated credit and the buyer’s intended purchase price.
What is the difference between contemplation by draw and by bid?
A draw selects eligible consortium members according to the group’s rules, while a bid involves competing through an offered amount. Both routes attribute the right to use the consortium credit, subject to contractual procedures. Neither automatically guarantees immediate payment because the administrator may still review the buyer, guarantees, documents and property.
I was selected in a property consortium. What do I do next?
Contact the administrator and obtain the updated quota statement, credit statement and current purchasing requirements. Then verify the available credit, required guarantees, eligible property category, documentation, appraisal and seller-payment procedure. The broker should confirm these conditions before promising a closing date or treating contemplation as immediately available cash.
How does an embedded bid affect the property credit?
An embedded bid uses part of the consortium credit to secure contemplation, so the net amount available for purchasing the property becomes smaller. Calculate it using the credit valid at the meeting minus the embedded-bid amount, both documented by the administrator. Any remaining purchase price and uncovered expenses require separate funding.
How long does it take to receive the credit after contemplation?
There is no verified universal deadline for releasing consortium credit after contemplation. Timing depends on the contract, administrator procedures, guarantees, property appraisal, documents and payment process. Brokers should request the current operational schedule directly from the administrator and align the offer and closing terms with documented milestones rather than an estimated date.
Is making a bid worthwhile if the client wants to buy a property soon?
A bid is worthwhile only when the client’s liquidity, opportunity cost and resulting purchasing capacity support it. Review the contractual bid base, payment deadline, updated credit and any embedded portion. Do not rely on a universal winning percentage or promised date; compare the net credit with the property price and uncovered transaction expenses.
What’s the best way to confirm that a contemplated consortium can be used for a specific property?
Confirm applicability with the administrator before the buyer commits to the property. Review the current contract and regulations, quota statement, credit statement, guarantees, property eligibility, required documents, appraisal and seller-payment process. Also calculate any funding gap using the total acquisition price, documented uncovered expenses and net credit effectively available for release.
Imovitec
Turn data into next steps.
Take the Imovitec diagnostic and see where your best opportunities are.