Buy at Auction to Resell or Rent? How the Exit Strategy Changes Due Diligence
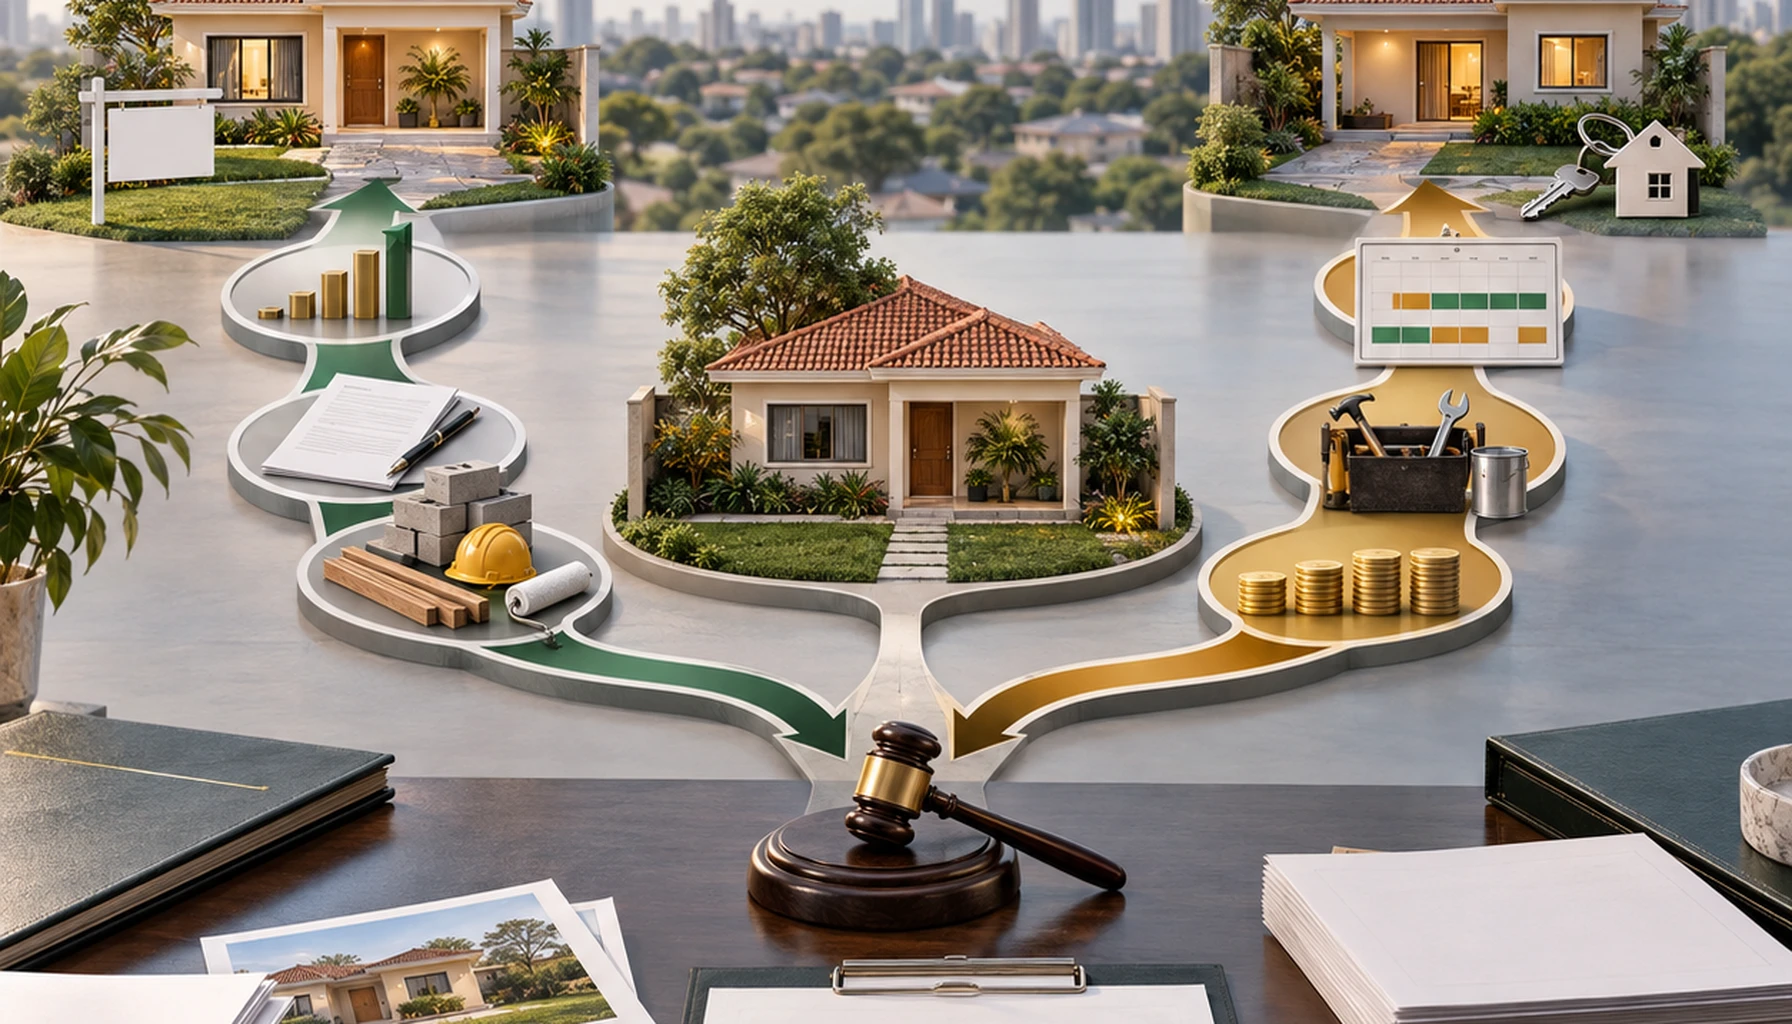
Choosing between resale and rental should happen before an auction bid, not after the property is won. The intended exit determines which documents, costs…
Imovitec · October 10, 2026
Choosing between resale and rental should happen before an auction bid, not after the property is won. The intended exit determines which documents, costs, risks and dates require investigation. It also changes the calculation used to decide whether a defensible maximum bid exists.
Neither exit is generally better. The answer depends on the property, location, possession, liabilities, tax treatment, timeline and locally supported assumptions. Where material evidence is missing, the analysis should use a disclosed adverse scenario or stop without setting a bid ceiling.
Key takeaways
Auction due diligence should begin with the intended exit because resale and rental produce different cash flows. Resale depends on future net sale proceeds. Rental depends on recurring net income after possession, regularization and preparation. Both routes require current documents, local evidence, an explicit calendar and reviewed legal and tax assumptions.
- Work backward from conservative net sale proceeds when testing resale.
- Divide stabilized net income by total invested capital when testing rental.
- Put possession, regularization, renovation and marketing on a dated calendar.
- Treat asking prices as leads, not proof of completed transaction values.
- Compare differently timed cash flows at the same valuation date.
- Use ranges or adverse cases for material unknowns. Never enter an unsupported zero.
- Withhold the bid if an unresolved issue could eliminate the required return.
Why does the exit strategy change auction due diligence?
The exit changes due diligence because resale concentrates the expected return in a future sale, while rental depends on recurring income after the property becomes legally and physically rentable. This is a financial inference, not a sourced market rule. Applying it requires evidence tied to the property and its location.
A broker advising an auction buyer should build two calendars. The first covers payment, registration, possession, regularization and renovation. The second ends either when net sale proceeds are received or when rental operation reaches a stabilized 12-month period.
Exit strategy: the planned route for realizing value from the property, such as resale or recurring rental income.
The auction notice, updated registry record and relevant certificates remain central in both cases. The guide to reading a Brazilian property auction notice before setting a maximum bid explains why the advertised conditions must be reconciled with the legal and property records.
What must be checked before either exit is evaluated?
Before comparing resale and rental, confirm that the available evidence can support either calculation. The minimum review covers the auction notice, updated registry record, relevant certificates, occupancy, known debts, possible subrogation rules and the governing auction procedure. Legal conclusions still require case-specific professional review.
The investigation should establish:
- who occupies the property and the asserted basis for that occupation;
- the legal and practical route to possession;
- condominium fees, IPTU and other obligations that may affect the asset or possession;
- registered liens, lawsuits, appeals and ownership-chain inconsistencies;
- permitted use, licensing, habitability and zoning constraints;
- the renovation scope, supported by itemized budgets;
- dated sale and rental comparables, including material physical and legal differences.
These facts change both the amount and timing of cash flows. The article on property-auction due diligence in Brazil provides a document-focused review.
Legal context must be stated carefully. In a specific contractual dispute, the Superior Court of Justice, or STJ, reported on April 16, 2021, that the absence of registration of a fiduciary transfer could prevent automatic application of the special procedure under Law 9,514/1997. In April 2026, the STJ selected a related controversy for repetitive-appeal treatment, but selection is not a final holding. Neither item establishes a universal rule for every auction. See the 2021 STJ report and 2026 STJ report.
Condominium liability also needs individual analysis. The STJ’s 2022 jurisprudence compilation, referring to Theme 886, indicates that possession and the condominium’s knowledge can matter alongside registration. Applying that principle to an auction buyer requires the full precedent, notice, registry record and possession facts. Consult the STJ’s 2022 compilation.
How should due diligence work for a resale exit?
For resale, due diligence must estimate the effective sale price, every cost needed to reach closing and the time until net proceeds arrive. The maximum bid is the residual amount after those costs and the investor’s documented minimum profit have been deducted. No universal discount or profit margin is supported here.
Expected net resale profit equals the effective sale price minus the bid, auctioneer’s commission, ITBI when due, registration, assumed debts, legal regularization, possession costs, renovation, condominium charges, IPTU, insurance, financing or cost of capital, sale brokerage and applicable taxes.
Each input should come from current documents, municipal and registry information, condominium records, itemized budgets, local transaction evidence and tax advice. Keep cents in the working calculation, present the result in reais and round the final maximum bid downward.
Asking prices are useful leads, but they do not prove the completed sale price, negotiation period or seller’s net proceeds. Comparables should be adjusted for location, area, condition, parking, legal status and evidence date. If completed transaction data are unavailable, retain a clearly identified range.
The resale maximum bid equals conservative net sale proceeds minus acquisition, possession, regularization, renovation, holding, sale and tax costs, minus the investor’s documented minimum profit.
Unknown possession timing, liabilities or costs should enter an adverse scenario or block the bid. They must not be entered as zero.
How does tax treatment affect resale?
For an individual resident in Brazil, capital gain is the positive difference between disposal value and acquisition cost, subject to applicable rules, reductions and exemptions. This definition appears in the federal GCAP service page, modified July 7, 2026. The page is operational guidance and does not replace legislation or tax advice.
Law 13,259/2016 establishes progressive individual capital-gains rates, beginning at 15% for the portion of gain not exceeding R$5 million. The remaining brackets, consolidated law and rules effective on the taxable-event date must also be checked in the official text of Law 13,259/2016.
The Federal Revenue Service states that a Brazilian resident individual may qualify for an exemption when proceeds from the sale of residential property are applied within 180 days to purchase residential property in Brazil, subject to legal conditions. Do not assume that an auction purchase intended for resale qualifies, or that the rule applies to a company or habitual trading activity. Review the Federal Revenue Service exemption guidance, GCAP and professional advice.
The second ends either when net sale proceeds are received or when rental operation reaches a stabilized 12-month period.
How should due diligence work for a rental exit?
For rental, due diligence should estimate stabilized net annual income and divide it by total invested capital. Dividing gross rent by the winning bid omits the capital needed to obtain possession, complete regularization, prepare the property and carry it through periods without rental income.
Gross annual yield: twelve times supported monthly rent, divided by total invested capital, expressed as a percentage per year.
Total invested capital includes acquisition, possession, regularization and preparation costs. It excludes expenses that would arise only from a future sale. Rent must be supported by current, genuinely comparable local evidence.
Stabilized net annual yield: effective annual revenue after recurring owner costs, divided by total invested capital for a stabilized 12-month period.
Recurring deductions may include vacancy, default, administration, maintenance, insurance, taxes and owner-paid charges. Months without possession or during renovation belong in the implementation cash flow. They must not disappear from the analysis.
The distinction is examined further in gross rent versus net rent. This evidence package supports no generic percentage for vacancy, maintenance or administration. Each input requires local evidence or an expressly labeled scenario.
Break-even monthly rent equals annual recurring costs plus the required annual return on total invested capital, divided by 12 and by expected occupancy.
The denominator represents an effectively occupied month. Use documented occupancy assumptions and present the result in whole reais. If occupancy evidence is unavailable, test several disclosed scenarios instead of selecting one as certain.
For rent received by an individual from another individual, the Federal Revenue Service’s Perguntas e Respostas IRPF 2026, version 1.00 dated April 23, 2026, states that certain taxes, fees and expenses may be excluded when the landlord bears them and the fiscal conditions are met. The guide generally concerns the 2026 filing year and typically 2025 events. It does not make every renovation, maintenance or condominium expense deductible. Consult the official IRPF 2026 guide.
Talk to a specialist
Want to see this applied to your case?
Instead of finishing the article and staying in theory, send us your situation on WhatsApp. We reply with the concrete next step.
How do possession and time alter both exits?
A possession delay postpones resale proceeds and increases holding costs. For rental, it postpones the first rent and can make an attractive stabilized yield irrelevant during implementation. Both calculations therefore need a dated possession scenario containing legal costs, condominium charges, IPTU, insurance, security and cost of capital.
The starting point for occupancy charges under fiduciary transfer is governed by Law 9,514/1997 and interpreted by the STJ. A 2021 STJ judgment concerns the period between auction disposal and entry into possession, but its complete facts, holding and the current statutory text require review before application. Occupancy charges are a legal-review item, not automatic income.
The article on an occupied auction property explains how possession timing enters the bid calculation.
How can resale and rental be compared fairly?
Resale and rental should be compared by bringing differently timed cash flows to the same valuation date. Net present value, or NPV, does this by discounting each period’s cash flow. The method must include the initial investment, intermediate costs and income, and the net residual value.
Net present value: the sum of each period’s cash flow divided by one plus the discount rate raised to that period.
Use monthly or annual periods consistently. The discount rate should reflect the investor’s documented opportunity cost, chosen periodicity and risk assessment. It is not supplied by the cited sources.
Maintain cents in the calculation and present the result in reais. Material unknowns should appear as ranges or scenarios. A sensitivity review should identify which assumption most changes the decision, such as possession timing, effective sale price, renovation cost, rent, occupancy or tax treatment.
When is there enough evidence to set a maximum bid?
A maximum bid is supportable only when it can be traced to current documents, defensible local comparables, itemized budgets, a realistic calendar and reviewed legal and tax assumptions. If a material unknown could eliminate the required return, the proper conclusion is “bid ceiling not established.”
The final recommendation should record:
- the intended exit and viable fallback;
- the date and scope of the evidence;
- unresolved legal, tax, physical and financial issues;
- the base and adverse scenario ranges;
- the assumption with the greatest sensitivity;
- the exact condition that would stop the bid.
That record documents a decision. It does not promise a return.
What are the sources and publication limitations?
The cited materials support specific tax and legal statements, not a forecast for any property. Legal sources concern defined disputes or summaries and require current, case-specific review. Tax guidance can change with the taxpayer, transaction and taxable-event date. No national claim that resale or rental performs better is supported.
- Federal GCAP service, modified July 7, 2026.
- Federal Revenue Service guidance on exempt transactions, accessed October 10, 2026.
- Law 13,259/2016, accessed October 10, 2026.
- Perguntas e Respostas IRPF 2026, version 1.00 dated April 23, 2026.
- STJ report dated April 16, 2021.
- STJ judgment made available June 11, 2021.
- STJ jurisprudence compilation for 2022.
- STJ report dated April 23, 2026.
No Imovitec call to action appears because the approved editorial brief contains no verified offer or supported next action for this audience and decision.
FAQ
How do I decide whether to resell or rent an auction property?
Choose the exit before bidding by comparing property-specific cash flows and timelines. For resale, estimate the net sale price, selling period, taxes, works and carrying costs. For rental, estimate net rent, vacancy, maintenance and time until productive possession. If material inputs remain unsupported, test an adverse scenario or do not bid.
When is it better to sell an auction property rather than rent it?
Resale may be preferable when a conservative net sale value supports the required profit after every acquisition, possession, renovation, carrying, selling and tax cost. There is no universal rule. The decision must rely on current local transaction evidence, an explicit timeline and a documented comparison with the rental alternative.
What's the best way to check whether an auction property can generate rental income?
Estimate stabilized net rental income using comparable local leases, expected occupancy, default risk, management, maintenance, insurance, taxes and owner-paid charges. Divide that income by total invested capital, not merely the winning bid. Keep possession delays and renovation months in the implementation cash flow rather than hiding them from the calculation.
How can I find out whether an auction property is occupied before bidding?
Occupancy must be investigated through the auction notice, updated land registry record, case documents, available certificates and lawful on-site verification. The evidence should identify occupants, existing leases and the likely possession process. Because possession rules depend on the auction and facts, legal review is necessary before assigning a deadline or cost.
What changes in due diligence when preparing an auction property for sale instead of rent?
Resale due diligence emphasizes the achievable net sale price, buyer demand, sales expenses, taxes and time to receive proceeds. Rental due diligence emphasizes lawful use, habitability, local rent, vacancy and recurring owner costs. Both require review of title, liabilities, possession, works, municipal rules and an explicit cash-flow schedule.
Does an auction discount guarantee a profitable resale or attractive rental return?
An auction discount does not guarantee profit or yield because the reference price may not represent an achievable transaction. Evaluate total invested capital, including the bid, auction fee, transfer and registration costs, assumed liabilities, possession, works, carrying costs and taxes. Use local evidence and scenarios instead of a generic discount or margin percentage.
Can one due-diligence model be applied to every Brazilian auction property?
A common framework can organize the analysis, but its inputs cannot be generalized across Brazilian properties. Auction terms, title, occupation, municipal costs, condominium obligations, permitted use, taxes and comparable prices vary by asset and location. Brokers should document each source, calculation date and uncertainty, then obtain legal and tax review where required.
Talk to a specialist
Have a real case to solve?
Message Imovitec on WhatsApp. We reply fast and already speak your context — no forms, no waiting.
Frequently asked questions
How do I decide whether to resell or rent an auction property?
Choose the exit before bidding by comparing property-specific cash flows and timelines. For resale, estimate the net sale price, selling period, taxes, works and carrying costs. For rental, estimate net rent, vacancy, maintenance and time until productive possession. If material inputs remain unsupported, test an adverse scenario or do not bid.
When is it better to sell an auction property rather than rent it?
Resale may be preferable when a conservative net sale value supports the required profit after every acquisition, possession, renovation, carrying, selling and tax cost. There is no universal rule. The decision must rely on current local transaction evidence, an explicit timeline and a documented comparison with the rental alternative.
What's the best way to check whether an auction property can generate rental income?
Estimate stabilized net rental income using comparable local leases, expected occupancy, default risk, management, maintenance, insurance, taxes and owner-paid charges. Divide that income by total invested capital, not merely the winning bid. Keep possession delays and renovation months in the implementation cash flow rather than hiding them from the calculation.
How can I find out whether an auction property is occupied before bidding?
Occupancy must be investigated through the auction notice, updated land registry record, case documents, available certificates and lawful on-site verification. The evidence should identify occupants, existing leases and the likely possession process. Because possession rules depend on the auction and facts, legal review is necessary before assigning a deadline or cost.
What changes in due diligence when preparing an auction property for sale instead of rent?
Resale due diligence emphasizes the achievable net sale price, buyer demand, sales expenses, taxes and time to receive proceeds. Rental due diligence emphasizes lawful use, habitability, local rent, vacancy and recurring owner costs. Both require review of title, liabilities, possession, works, municipal rules and an explicit cash-flow schedule.
Does an auction discount guarantee a profitable resale or attractive rental return?
An auction discount does not guarantee profit or yield because the reference price may not represent an achievable transaction. Evaluate total invested capital, including the bid, auction fee, transfer and registration costs, assumed liabilities, possession, works, carrying costs and taxes. Use local evidence and scenarios instead of a generic discount or margin percentage.
Can one due-diligence model be applied to every Brazilian auction property?
A common framework can organize the analysis, but its inputs cannot be generalized across Brazilian properties. Auction terms, title, occupation, municipal costs, condominium obligations, permitted use, taxes and comparable prices vary by asset and location. Brokers should document each source, calculation date and uncertainty, then obtain legal and tax review where required.
Imovitec
Turn data into next steps.
Take the Imovitec diagnostic and see where your best opportunities are.