Off-Plan Property as a Wealth Decision: What to Assess Beyond Price
An off-plan property is not merely a unit carrying an advertised price. It sets in motion contractual instalments, monetary adjustments, credit choices…
Imovitec · September 21, 2026
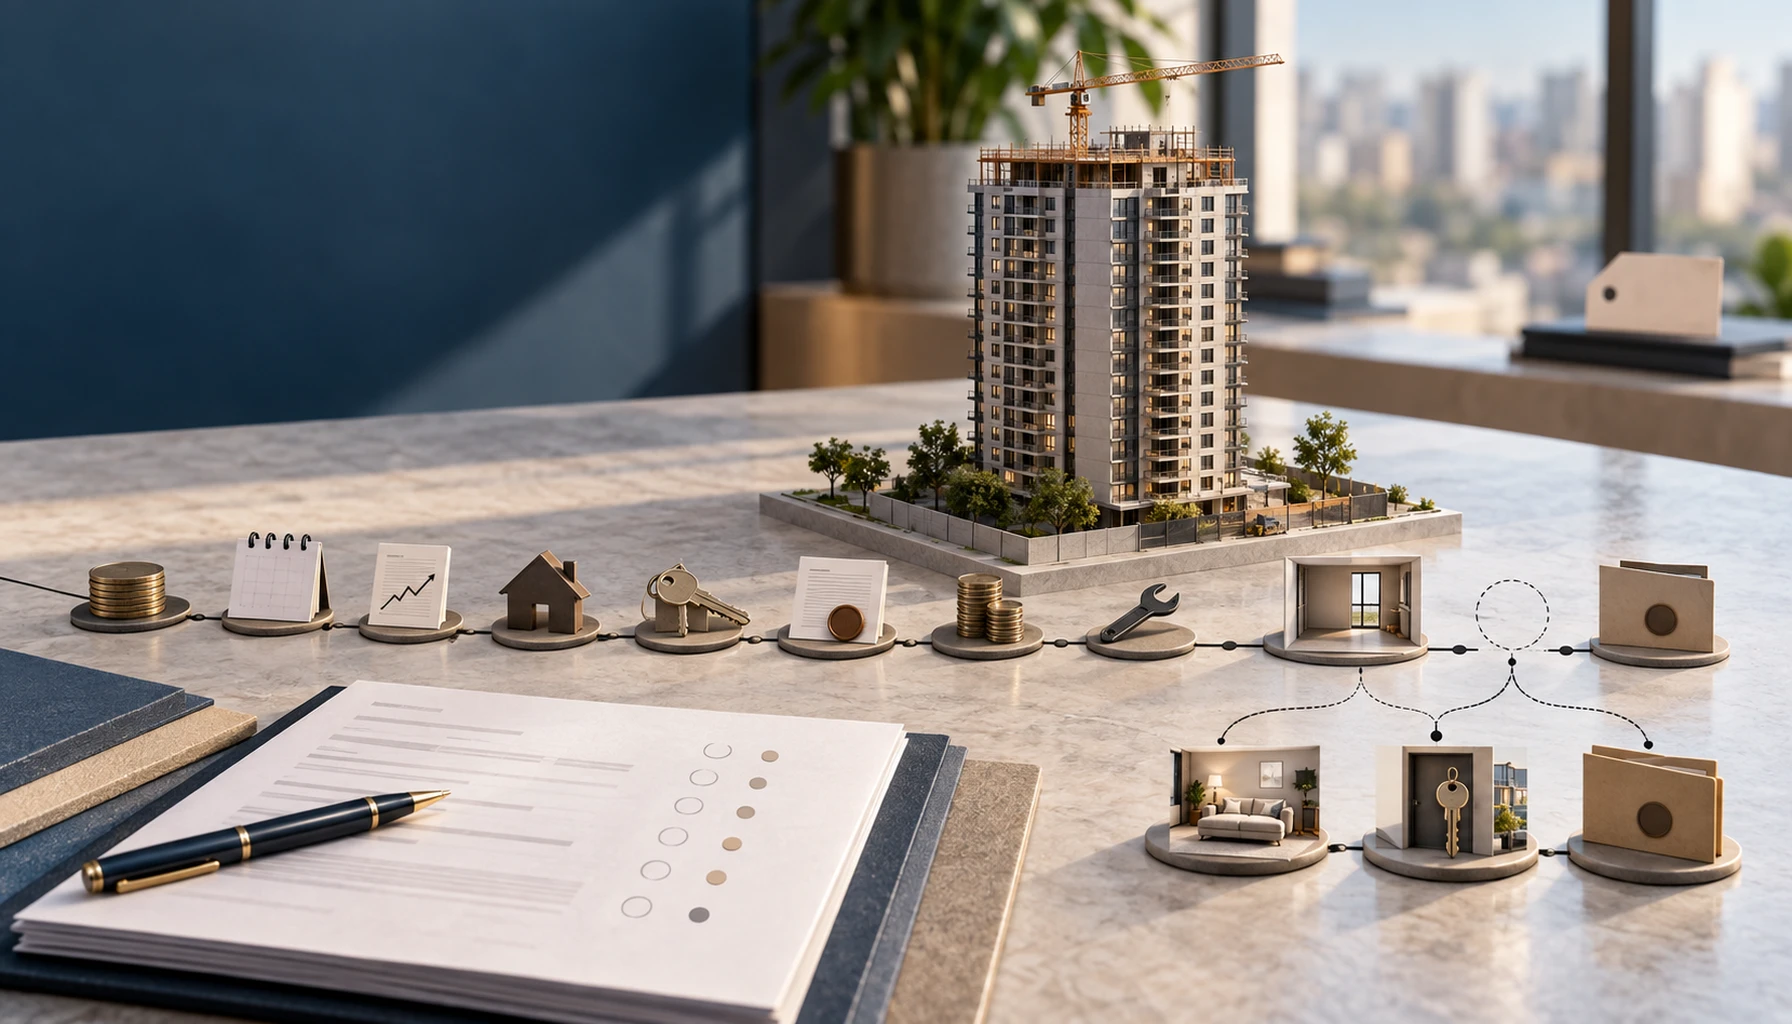
An off-plan property is not merely a unit carrying an advertised price. It sets in motion contractual instalments, monetary adjustments, credit choices, ownership expenses and potential exit costs. The practical issue is whether this entire cash flow suits the buyer’s resources, purpose and time horizon.
For a consultative residential-launch broker, that broader view changes the recommendation. Documented facts must be separated from assumptions and unresolved figures. The intended use also needs its own test: occupation, rental or sale.
Key takeaways
A sound assessment tracks the buyer’s complete cash flow from contract signing to the chosen valuation or disposal date. Missing costs are not zero, future appreciation is not assured, and the advertised price does not represent the full capital commitment. Every material input needs documentation or an unresolved status.
- The advertised price is only one component of the decision.
- Contractual adjustments, financing, taxes, registration charges, buyer-paid brokerage, condominium fees, maintenance, vacancy and selling expenses may alter the outcome.
- An unavailable amount means “not determined,” never zero.
- Appreciation, rental return and net present value require comparable dates, consistent denominators and verified inputs.
- The contract summary and patrimônio de afetação are relevant legal checks, but their effects depend on the development and contract.
- The approved evidence does not support publishing market rates, index levels, appreciation, rental yields, sales volumes or liquidity claims.
What does it mean to treat an off-plan property as a wealth decision?
Treating an off-plan property as a wealth decision means examining its full contractual and economic timeline. Required payments, adjustment provisions, financing, ownership costs and the intended outcome belong in the same assessment. Off-plan property is not inherently good or bad; the conclusion rests on documented terms and demonstrable cash flows.
Concise definition: A wealth decision evaluates the property’s full cash flow and intended use, not only its advertised price.
What is the buyer trying to achieve, and over what period? The broker needs those answers before testing the proposed schedule against available resources and later obligations.
Similar advertised prices can conceal different payment dates, adjustment clauses, financing needs and post-delivery expenses. That observation supports comparison, but it does not prove that either unit is cheaper. The initial review can begin with how to read a Brazilian developer sales table before buying off-plan.
Which amounts belong in the total-cost calculation?
Total nominal cost covers all documented buyer outflows, less documented net income, over a stated period. The time frame runs from contract signing to the selected valuation or disposal date. Transaction records, applicable official tables or property records must support every component.
Total nominal cost equals the down payment, periodic instalments, balloon payments, payment at handover, contractual adjustments, financing interest and fees, taxes, registration charges, buyer-paid brokerage, condominium and maintenance expenses, and selling costs, less net income.
The unit is Brazilian reais per property. Keep cent-level precision throughout the calculation and present the total in reais with two decimal places. If a component has not been established, label it “not determined.”
Never substitute zero for missing evidence.
The evidence file should contain:
- the signed contract and contract summary;
- the complete payment schedule, including balloon and handover payments;
- the adjustment clause and the official series named in it;
- the lender’s proposal, charges and financing conditions;
- municipal and registry tables applicable to the location and date;
- evidence showing who bears the brokerage cost;
- documented condominium, maintenance, insurance and administration expenses;
- evidence of rent received or net sale proceeds, where relevant.
This method extends the analysis in the total cost of an off-plan property in Brazil. A universal cost figure would be unsupported because the evidence package covers no specific property.
How should contractual monetary adjustment be calculated?
Contractual monetary adjustment must follow the index, base date, frequency and method written into the contract. The index name alone cannot settle the calculation. Both the adjustable balance and the relevant dates affect the amount, leaving the result pending until the clause and official series are available.
When the contract adopts this method, the adjusted balance for a period equals the base balance multiplied by the period index and divided by the base-date index. An equivalent contractual formula may apply instead.
Express the result in reais for the balance covered by the clause and observe the stated frequency. Retain full precision while calculating, then round only the monetary result.
A missing index observation cannot be interpolated unless a documented rule allows it. Publication delays must also be recorded. No index level or forecast appears here because the approved research did not recover a supporting primary publication.
Talk to a specialist
Want to see this applied to your case?
Instead of finishing the article and staying in theory, send us your situation on WhatsApp. We reply with the concrete next step.
Which legal documents affect the risk assessment?
The contract, contract summary and records describing the development’s legal structure help reveal obligations and risks. Their practical consequences depend on the transaction under review. They are evidence for analysis, not blanket assurances of compliance, delivery or financial safety.
According to the Brazilian Chamber of the Construction Industry, or CBIC, patrimônio de afetação legally separates the land, improvements and other assets and rights connected with a development. Confirmation is still required for the particular project, both as to its existence and its effects. The CBIC guide is explanatory sector material, not consolidated legislation, and its internal publication date and update status were not verified (CBIC guide, accessed September 21, 2026).
Concise definition: Patrimônio de afetação is the legal segregation of assets and rights linked to a particular real-estate development.
Event material hosted by the Central Bank of Brazil discusses Law 10,931/2004 and this segregation mechanism. Dated March 18, 2010, the presentation has an external author, is not Central Bank regulatory guidance and may be outdated (event presentation, accessed September 21, 2026). See what patrimônio de afetação may change if the developer fails.
The approved evidence further indicates that Law 13,786/2018 introduced requirements concerning the contract summary and addressed consequences of terminating acquisition contracts in real-estate developments. Legal review remains necessary for its consolidated wording and its application to a particular agreement. This article cannot support any retention percentage, refund period, delivery tolerance or categorical brokerage rule.
How can a broker test occupation, rental and sale?
A broker can model occupation, rental and sale as three distinct scenarios built on the same documented acquisition cash flow. Each introduces different expenses, income and uncertainties. Combining them would hide material distinctions and risk presenting unverified assumptions as an expected outcome.
Event material hosted by the Central Bank of Brazil discusses Law 10,931/2004 and this segregation mechanism.
Living in the property
For owner occupation, add documented financing, taxes, registration, condominium fees, maintenance and other ownership expenses to the acquisition flow. The decision consequence is straightforward: both the initial payments and continuing obligations must fit the buyer’s resources.
Municipal tax or registration amounts cannot be calculated without the municipality, taxable-event date, assessment base and applicable official table. Until those records are obtained, the inputs remain unresolved.
Renting the property
Net rental return equals rent actually received, less vacancy, default, taxes, non-recoverable condominium charges, maintenance, management and insurance, divided by average capital invested over the same period.
Use average capital invested in the property as the denominator. The result applies to the selected monthly or annual period, without mixing frequencies, and should be presented to two decimal percentage points.
Months without records are data gaps. They are neither occupied months nor zero-rent months. Without property records and a consistent time frame, any yield claim remains blocked. The distinction is examined further in gross rent versus net rent.
Selling or assigning the position
A sale assessment starts with documented net proceeds after applicable selling expenses. Nominal appreciation equals final value divided by a comparable cost base, minus one. Real appreciation equals one plus nominal appreciation, divided by one plus comparable accumulated inflation, minus one.
Both formulas must concern the same property over an explicitly stated period. Retain four decimal places during the calculation and present the outcome to two decimal percentage points. Non-comparable dates, property standards or cost bases block the conclusion.
Before completion, an exit may take the form of an assignment or contract termination, depending on the documents and circumstances. Retention and repayment consequences may vary with the legal regime, contract date, presence of patrimônio de afetação and facts of the case.
An article published by the Brazilian Association of Real Estate Developers, or ABRAINC, on December 12, 2025 discusses a Superior Court of Justice decision related to the termination law. ABRAINC is an interested secondary source; its article does not replace the judgment, legislation or legal advice (ABRAINC, accessed September 21, 2026). See also contract termination versus assignment.
When should the buyer advance, compare or pause?
The buyer should advance only after material cash-flow inputs and contractual conditions are documented and found compatible with the stated objective. Another structure should be compared on equivalent terms if it may fit better. A material unresolved cost, clause, financing condition or exit assumption calls for a pause.
Use three decision statuses:
- Advance: Material documents are available, inputs are traceable and the tested cash flow fits the buyer’s objective and horizon.
- Compare: The evidence permits a like-for-like comparison, but another unit, schedule or contractual structure may fit better.
- Pause: A material document, adjustment rule, financing condition, ownership cost or exit assumption remains unresolved.
Net present value can aid comparison when the complete cash flow and a justified discount rate are available. It is the sum of each positive or negative cash flow divided by one plus the discount rate raised to its corresponding uniform period.
The unit is reais at the selected base date. Retain cents in the calculation and present the result in reais with two decimal places. A missing cash flow or unjustified discount rate blocks the result; presumed future appreciation cannot fill the gap.
Disciplined qualification is the broker’s contribution: identify documented evidence, analytical inference and remaining unknowns. The resulting recommendation is auditable and does not disguise uncertainty as certainty.
FAQ
What does buying an off-plan property actually mean?
An off-plan purchase means signing for a unit before construction is complete and assuming a contractual payment schedule through delivery. The decision should consider the contract, summary sheet, monetary-adjustment rule, developer and lender documents, possession costs, and the intended outcome: occupancy, rental, or resale. Legal terms require case-specific review.
What costs are included when buying an off-plan property?
The acquisition cost includes every documented cash outflow, not merely the advertised price. Depending on the contract and location, this may cover the deposit, installments, balloon payments, contractual adjustments, financing charges, taxes, registration fees, buyer-paid brokerage, condominium fees, maintenance, and exit costs. Missing components should remain “not determined,” never zero.
How do I calculate the appreciation of an off-plan property?
Appreciation is calculated by comparing the property’s documented final value with a comparable, clearly defined cost base over matching dates. Nominal appreciation equals final value divided by the cost base, minus one. A real-return estimate also requires comparable official inflation data. Without reliable values, dates, and comparable property standards, the calculation should be withheld.
Is buying an off-plan property really cheaper?
An off-plan property cannot be assumed to be cheaper without a like-for-like comparison of total costs. Compare equivalent units, dates, payment conditions, contractual adjustments, financing, taxes, fees, possession expenses, and exit costs. Advertised-price discounts alone do not establish savings, appreciation, superior returns, or lower financial risk.
How does the payment schedule for an off-plan property work?
The payment schedule follows the signed contract and may distribute cash outflows across the deposit, periodic installments, intermediate payments, delivery, and financing. Each broker should map amounts, due dates, adjustment rules, and unresolved financing conditions from documentary evidence. No index, interest rate, or future credit approval should be presumed without verified sources.
How can a broker determine whether an off-plan property offers an acceptable return?
An acceptable return depends on documented cash flows, the buyer’s objective, and a justified comparison benchmark. Model all contributions and net proceeds through occupancy, rental, or sale, including vacancy and exit costs when applicable. If future appreciation, rent, financing terms, or the discount rate lacks evidence, present scenarios as unresolved rather than promised outcomes.
What is the most reliable way to qualify an off-plan opportunity for a client?
The most reliable method is a documented, property-specific review of the complete contractual cash flow. Verify the contract, summary sheet, adjustment formula, developer and lender documents, applicable official tables, ownership costs, and exit evidence. Separate confirmed facts from assumptions and gaps, then recommend advancing, comparing, or pausing the analysis accordingly.
Talk to a specialist
Have a real case to solve?
Message Imovitec on WhatsApp. We reply fast and already speak your context — no forms, no waiting.
Frequently asked questions
What does buying an off-plan property actually mean?
An off-plan purchase means signing for a unit before construction is complete and assuming a contractual payment schedule through delivery. The decision should consider the contract, summary sheet, monetary-adjustment rule, developer and lender documents, possession costs, and the intended outcome: occupancy, rental, or resale. Legal terms require case-specific review.
What costs are included when buying an off-plan property?
The acquisition cost includes every documented cash outflow, not merely the advertised price. Depending on the contract and location, this may cover the deposit, installments, balloon payments, contractual adjustments, financing charges, taxes, registration fees, buyer-paid brokerage, condominium fees, maintenance, and exit costs. Missing components should remain “not determined,” never zero.
How do I calculate the appreciation of an off-plan property?
Appreciation is calculated by comparing the property’s documented final value with a comparable, clearly defined cost base over matching dates. Nominal appreciation equals final value divided by the cost base, minus one. A real-return estimate also requires comparable official inflation data. Without reliable values, dates, and comparable property standards, the calculation should be withheld.
Is buying an off-plan property really cheaper?
An off-plan property cannot be assumed to be cheaper without a like-for-like comparison of total costs. Compare equivalent units, dates, payment conditions, contractual adjustments, financing, taxes, fees, possession expenses, and exit costs. Advertised-price discounts alone do not establish savings, appreciation, superior returns, or lower financial risk.
How does the payment schedule for an off-plan property work?
The payment schedule follows the signed contract and may distribute cash outflows across the deposit, periodic installments, intermediate payments, delivery, and financing. Each broker should map amounts, due dates, adjustment rules, and unresolved financing conditions from documentary evidence. No index, interest rate, or future credit approval should be presumed without verified sources.
How can a broker determine whether an off-plan property offers an acceptable return?
An acceptable return depends on documented cash flows, the buyer’s objective, and a justified comparison benchmark. Model all contributions and net proceeds through occupancy, rental, or sale, including vacancy and exit costs when applicable. If future appreciation, rent, financing terms, or the discount rate lacks evidence, present scenarios as unresolved rather than promised outcomes.
What is the most reliable way to qualify an off-plan opportunity for a client?
The most reliable method is a documented, property-specific review of the complete contractual cash flow. Verify the contract, summary sheet, adjustment formula, developer and lender documents, applicable official tables, ownership costs, and exit evidence. Separate confirmed facts from assumptions and gaps, then recommend advancing, comparing, or pausing the analysis accordingly.
Imovitec
Turn data into next steps.
Take the Imovitec diagnostic and see where your best opportunities are.